

This article is adapted from AQ’s special report on Mexico’s path forward
Time and again we hear the story of Latin America’s struggle to climb the global value chains and diversify beyond commodity exports. But the region is quietly building an impressive streak of wins in emerging high-tech sectors, and this evolution could soon amount to a major boom.
Last year, Mexico became the leading exporter of advanced technology products to the United States, surpassing Taiwan while nearly doubling such shipments from China. These products—from electronics and microchips to machinery and military hardware—are critical to industry and national security alike. Though Taiwan retook the lead in the first semester of this year, the deeper story is that Mexico’s high-tech exports to the U.S. continued to surge, growing 47% annually to $98.3 billion, according to the U.S. Census Bureau. As a result, the U.S. now depends on Mexico for 40% of its server center imports, which are essential to AI development.
The shift reaffirms a trend the United Nations Economic Commission for Latin America and the Caribbean (ECLAC) highlighted last November. “A geographical reconfiguration of global value chains is under way,” the institution argued in a seminal report about “trade in an era of weaponized inter-dependence.”
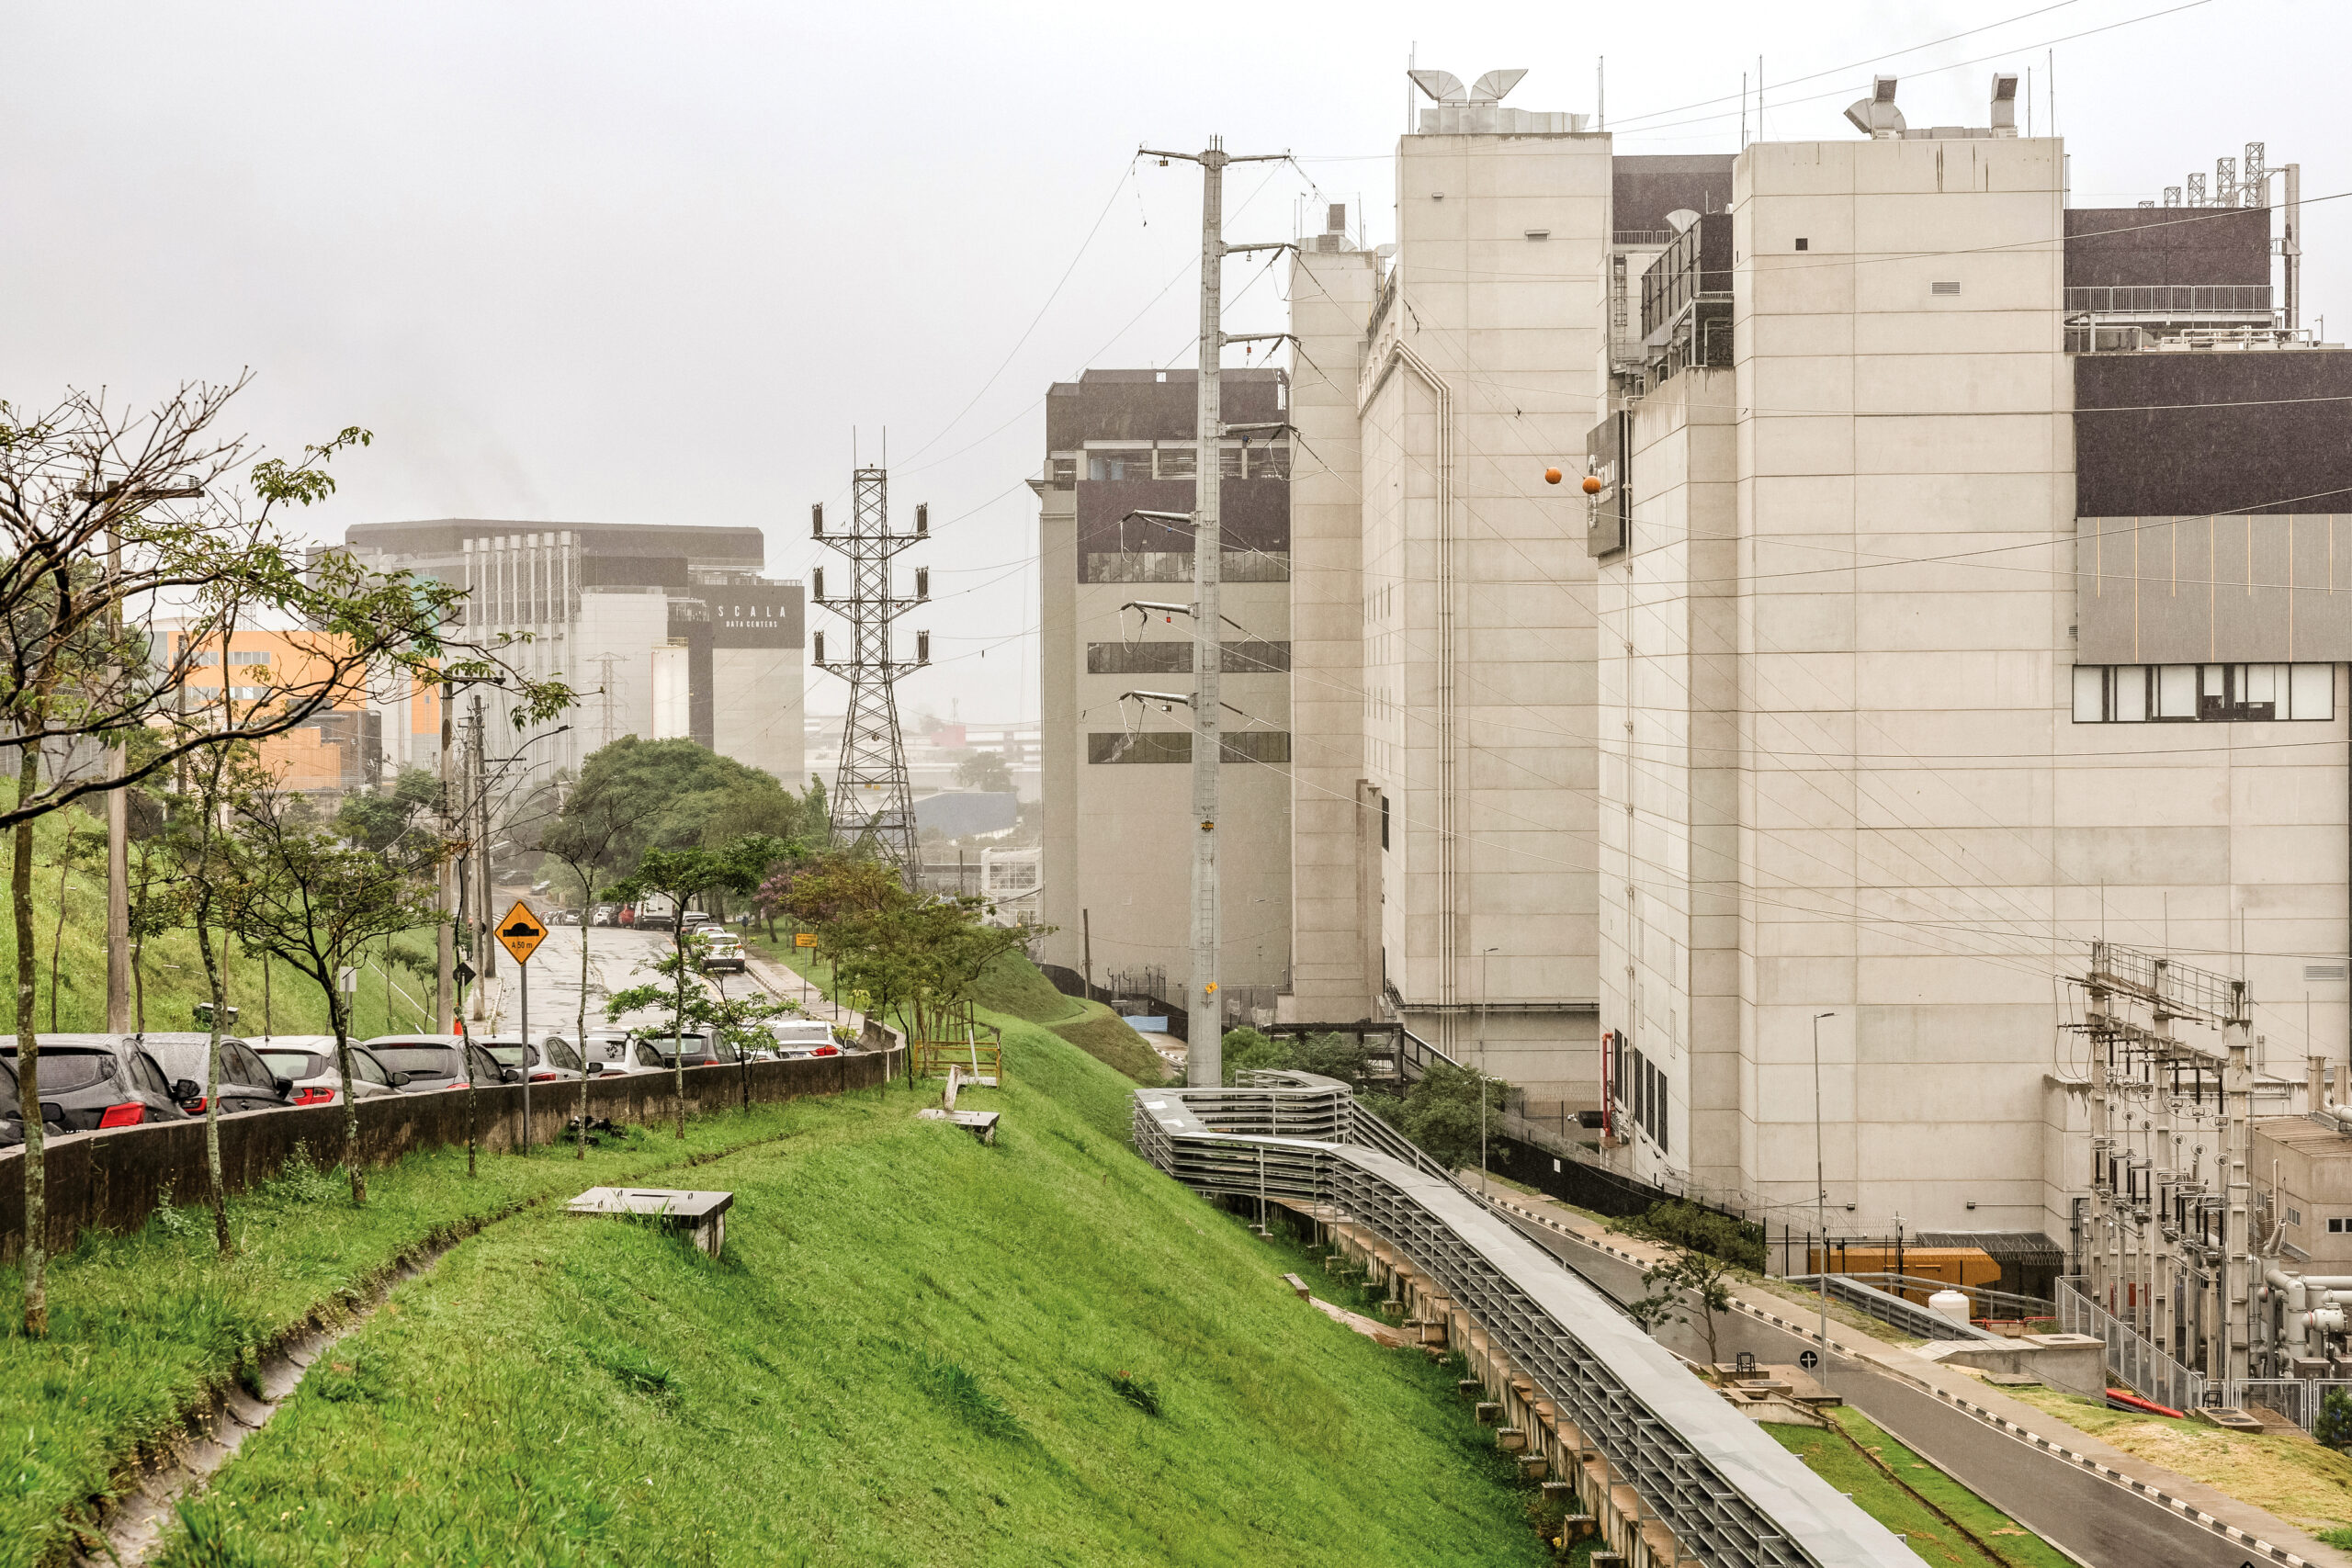
How is Latin America navigating this change? Encouraging signs abound. Brazil, the region’s largest tech and software market, is in the midst of a massive data center buildout to support its tech ecosystem and facilitate cloud- and AI-based service exports. Its stock of 218 data centers is the 11th largest worldwide, and that number is expected to grow dramatically over the coming four years: Experts forecast that the country’s 800 megawatts of data center capacity could expand to 2 gigawatts by 2030.
Even smaller players like Costa Rica and Uruguay have been punching above their weight in high-tech supply chains, while others like the Dominican Republic and Panama are learning from them as they aim to replicate their successes.
Meanwhile, global demand for high-tech hardware and services is soaring. Latin America is already beginning to harness the opportunities presented by both these trends. The region’s recent success offers valuable lessons and early clues for companies and governments on how to capitalize on this window of opportunity.
Mexico’s chip strategy
As the U.S. seeks to nearshore critical microchip supply chains, it is focused on supporting Mexico’s chip “assembly, testing and packaging” (ATP) capacity, and Mexico is rapidly taking up the mantle. Taiwan’s Foxconn is building what could be the world’s largest assembly facility for Nvidia GB200 superchips in Guadalajara, and across the northern border, other Taiwanese original design manufacturers (ODMs) are also investing heavily to advance high-tech products.
“Investment by Taiwan enterprises on both sides of the U.S.-Mexico border is reshaping North American supply chains,” Brendan Kelly, a visiting fellow at the Federal Reserve Bank of Dallas, argued in a report earlier this year.
But ATP is the lowest-value step in the microchip production process, and far more value resides in design and manufacture. That is why Mexico’s current industrial policy emphasizes design as well. The plan focuses on gains not in the most sophisticated chips, but in those used in most consumer goods, from cars and toasters to subway doors.
Perhaps counterintuitively, design facilities require far less capital than ATP facilities do. They can be built for around $200,000, compared to the $2-10 million outlay for an ATP facility. The challenge lies in training a workforce and funding research and development. To address this, Mexico is building out Kutsari, a national initiative to boost competitiveness in the chip supply chain. It is working with universities to train qualified workers and crafting legal reforms to streamline patents, safeguard intellectual property, and cut other red tape.
Central America’s education example
Few if any countries in Latin America have been more successful than Costa Rica at cultivating cooperation between the public and private sectors to build a qualified chips workforce. Known for its medical device sector, which accounts for about 40% of its exports, the country rolled out its chips sector strategy in 2024.
The country’s Centers of Excellence (COE) program works closely with the private sector. Universities offer students COE curricula designed in partnership with multinational companies, and students earn ATP certifications and other related skills. Costa Rican and U.S. companies have committed over $45 million in funding to the COE program. Although Intel Corp. recently announced it would shut down its chip center in Costa Rica in favor of Vietnam, at least a dozen other companies still operate in this field. Like Mexico, Costa Rica also made important reforms to guarantee intellectual property rights alongside its education and training initiatives.
The Dominican Republic seems to be learning from Mexico and Costa Rica, building on its recent success in overall electronics exports, which rose 50% from 2018 to 2023. Many of those exports are produced in the country’s more than 80 FTZs, and about 99% of those go straight to the U.S. The OECD called its FTZ framework a key strength for its attempts to attract ATP investment, and the government is investing assertively in domestic research and development.
The data center boom
Latin America’s gains in hardware exports are encouraging, as are its exports of information and communication technology (ICT) services. The region’s ICT services exports nearly doubled in just four years from 2020 to 2024. Meanwhile, in the most recent available regional report on the sector, ECLAC estimates that AI already contributed $70.7 billion, or 1.1% of the region’s GDP, in 2023.
Data centers are a fundamental pillar of digital infrastructure and will be key to maintaining progress across sectors. The region invested over $2 billion in data centers in 2024 alone, and the data center market could double over the next four years.
Global data center demand is expected to grow 15% every year, and in Latin America, Brazil is leading the way, attracting over 40% of the investment flowing into the sector. According to Brazil’s finance ministry, its new incentive framework could draw $377 billion in new investment over the next decade. Its renewable energy prowess (over 80% of its electricity comes from renewables) and water infrastructure are also major advantages.
Mexico is the region’s runner-up, seeking to connect data center development not only to its own tech hubs, but also to facilities across the U.S. border. Querétaro, one of the focal points of the Kutsari initiative, garnered $4.9 billion in investments for six data centers last year alone. The country lacks Brazil’s clean-energy abundance and is taking steps to mitigate these shortfalls, including the 2025 electricity law that fast-tracks industrial park power-generation projects, but progress will take time.
Adding value to the supply chain is within reach, and the region has already begun to climb. It can learn a lot from what has paved the way so far. Governments invested in research and development, and coordinated closely with the private sector to build up workforces ready to tackle the challenges of new technologies. They passed public policies to protect intellectual property and cut red tape, and created tax incentives and free trade zones. They scaled up renewable energy and created the regulatory frameworks necessary to pair new power generation with industrial projects.
Latin America is no stranger to potential—or to frustrated hopes. But these initiatives show that across high-tech sectors, concrete and significant gains are possible. Sustaining and expanding this trend into other segments of the value chain and other countries is part of the ongoing test for all decision-makers involved.
ABOUT THE AUTHORS
Nur Cristiani
Reading Time: 5 minutesCristiani is the head of LATAM investment strategy at J.P. Morgan’s Private Bank
Rich Brown
Reading Time: 5 minutesBrown is an editor and production manager at Americas Quarterly
Can Latin America Become a Data Center Powerhouse?
An ongoing boom suggests major opportunities lie ahead, but only if the region invests in education and worker training.