

This article is adapted from AQ’s forthcoming issue on Mexico’s path forward
For a quarter of a century, the economic consequences of China’s rise on the global stage have been interpreted through the idea of the China Shock: the disruptive flow of products the country began selling to the world as it became the ultimate manufacturing hub. Today, a different phenomenon is emerging with equal, if not greater, repercussions for all.
The question is no longer simply how economies absorb the volume and competitiveness of Chinese exports, but how they manage their dependence on strategic products, technologies, and industrial inputs that China controls—and may decide to withhold. There is also a less-discussed dimension: What happens when China buys less from the world while concentrating its purchases among a smaller number of strategic suppliers? That’s what I call the “China Choke.”
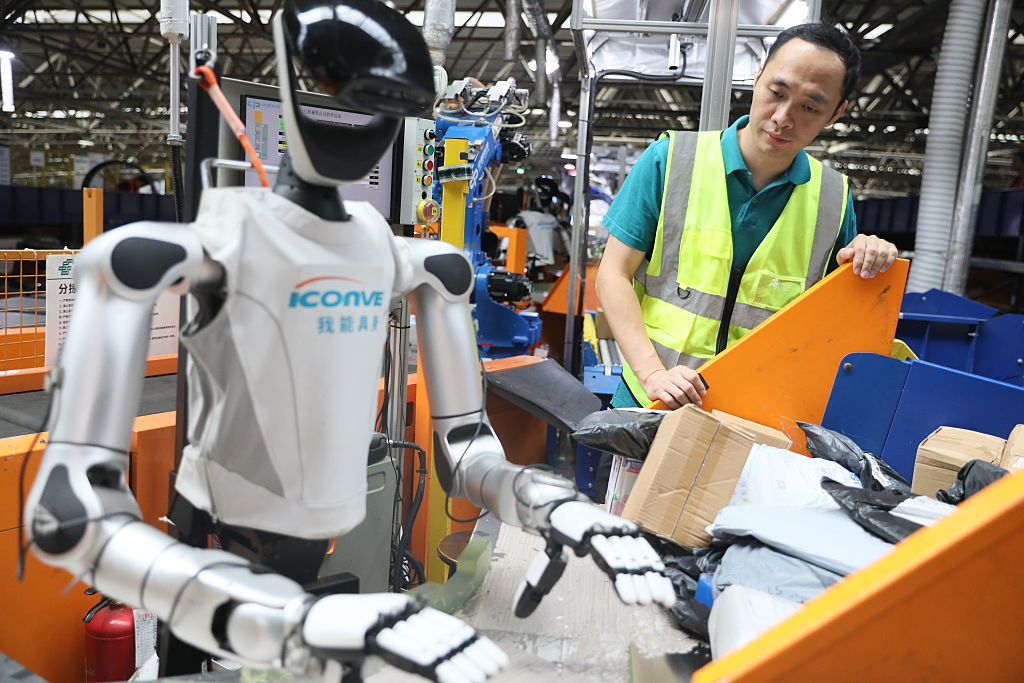
The China Shock described the impact of China’s rapid integration into the world economy, especially after its accession to the World Trade Organization in 2001. Hundreds of millions of Chinese workers entered the global labor force, multinational companies shifted production, and consumers gained access to cheaper goods. China became the factory of the world—lowering prices and lifting hundreds of millions of Chinese citizens out of poverty—while factories closed across the United States, Europe, and Latin America as manufacturing migrated to China.
Economists David Autor, David Dorn, and Gordon Hanson documented how Chinese import competition produced job losses in exposed regions of the U.S. In Latin America, the Shock was not the only cause of the region’s premature deindustrialization, but it played an important role. In the mid-1980s, Brazil was one of the Southern Hemisphere’s most important industrial hubs. Today, manufacturing accounts for only about 12% of its GDP.
The Shock concerned the disruptive consequences of the products China sold. The Choke concerns the strategic power the country derives from controlling what the world cannot easily obtain elsewhere.
China no longer occupies only the final-assembly stage. It has built commanding positions in critical minerals, rare-earth processing, permanent magnets, batteries, solar panels, and countless intermediate goods—bottlenecks it can exploit through export licensing, delays, or outright prohibitions. An interruption involving an inexpensive but irreplaceable component can paralyze an entire production system.
From efficiency to resilience
This represents a profound shift in the logic of globalization. During the post-Cold War era of hyperglobalization, efficiency was the principal organizing idea: produce wherever costs were lowest and source inputs wherever they were cheapest.
That world no longer exists as we once understood it. Pandemics, wars, sanctions, and geopolitical fragmentation have demonstrated that the pursuit of extreme efficiency can create dangerous fragility. The new objective is not maximum efficiency, but optimal resilience.
This is part of the shift from traditional ESG—environmental, social, and governance—to what I call ESG 2.0: economy, security, and geopolitics. Investment decisions are now evaluated not only on cost and return, but also through the lenses of national security and geopolitical exposure. Tariffs, export controls, subsidies, and industrial policy are once again instruments of statecraft.
Global interdependence has thus become a field of mutual vulnerability, in which supply chains can serve as instruments of coercion rather than merely as transmission belts for efficiency. Globalization is being reconfigured—through reshoring, nearshoring, and friendshoring—into shorter or more diversified chains increasingly organized around geopolitical affinity.
The limits of leverage
China also has vulnerabilities of its own: dependence on imported energy and agricultural commodities, exposure to foreign markets, demographic decline, a weakened property sector, and high domestic debt. Export restrictions can hurt Chinese manufacturers that rely on the same inputs and can invite retaliation. The Choke, therefore, does not describe unilateral dominance. It describes a system of reciprocal dependencies in which every country seeks control over strategic nodes while reducing its exposure to nodes controlled by others.
The geological lottery alone will not determine who benefits from the race for critical minerals. The key distinction is between possessing natural resources and playing a larger role in the value chains built on them. A country can export raw concentrate only to import the refined material at a much higher price. The real prize lies in processing, technology, and industrial applications.
Three groups of countries stand to gain. The first includes resource-rich economies such as Australia, Canada, and several Latin American nations. The second, led by countries such as Japan, South Korea, and the Netherlands, controls high-value technological nodes. These countries gain not by replacing China at scale, but by remaining essential and reliable. A third group—including India, Vietnam, Indonesia, and Mexico—is absorbing manufacturing investment as companies seek alternatives to excessive concentration in China.
No single country will replace China as the world’s factory. The more likely outcome is a distributed architecture of specialized hubs in which reliability and trusted delivery command a decisive premium.
The demand-side choke
A second, less-examined dimension of the China Choke concerns the consequences of China buying less—or buying differently. For a quarter century, China was an extraordinary engine of global demand, helping fuel one of history’s largest commodity supercycles. That pattern is unlikely to continue in the same form. China’s economy is slowing, and its growth model is placing greater emphasis on advanced manufacturing and technological self-reliance.
The Choke can therefore operate through demand as well as supply—not only through what China withholds from its exports, but through what it reduces, redirects, or concentrates in its imports. Countries heavily reliant on Chinese demand face significant exposure in export revenues, currencies, investment, and employment.
The more likely outcome is not a collapse in Chinese demand, but growing selectivity: purchases that are more concentrated among a smaller circle of suppliers considered reliable, strategic, and politically compatible. What emerges is not deglobalization, but narrower, more politically structured globalization. China may account for a smaller share of global import growth while directing a larger share of its purchases toward Latin America.
Latin America’s opening—and its catch
Latin America sits squarely within this transformation. It faces the risks of the China Choke but is unusually well positioned to benefit. This opportunity isn’t confined to one country; it spans several of the region’s economies.
Even as Chinese import growth slows, Beijing will continue to prioritize supply security in food, energy, and minerals—areas where reliability may matter more as aggregate demand cools. Brazil is already among China’s most important suppliers of soybeans, iron ore, oil, and animal protein. Chile and Peru are central to global copper supply, while Chile and Argentina hold major lithium resources. Argentina also possesses Vaca Muerta, one of the largest shale formations outside North America. Mexico occupies a different position: It is less a commodity supplier to China than a nearshoring beneficiary, able to attract manufacturing investment through its proximity to the U.S. These factors give Latin America potential leverage across minerals, energy, food, and manufacturing.
But the opportunity comes with a catch the region knows well. Latin America has heard versions of this story before, and converting resource abundance into industrial capability has repeatedly proved difficult. Infrastructure bottlenecks, complex tax systems, regulatory uncertainty, and permitting delays have blunted previous commodity booms before they could mature into durable development gains.
Whether Latin American countries capture this moment—or merely rent out their geology once again—will depend on regulatory predictability, competitive taxation, modern infrastructure, affordable energy, human capital, technological capacity, and deeper integration with international markets.
China will remain an essential commercial partner, while the U.S. and Europe will remain critical sources of technology, capital, and investment. Latin America’s objective should be strategic multi-alignment: engaging multiple poles while avoiding excessive dependence on any single market, supplier, technology, or financial channel.
Dependence is not interdependence
The distinction between the China Shock and the China Choke marks a genuine evolution in the world economy. The first was about prices, factories, and jobs. The second is about resilience, security, and power—the recognition that control over global value chains can matter as much as control over territory or military capabilities.
The lesson is not that countries should retreat from trade with China, or that interdependence must give way to autarky. Dependence and interdependence are not the same thing: Interdependence distributes vulnerability; dependence concentrates it.
The China Shock remade globalization by changing where the world produced. The China Choke is remaking it once again—by changing what the world considers secure, what China chooses to buy, and from whom.
For Latin America, the challenge is greater than avoiding another missed commodity cycle. It is to transform this historic realignment into the foundation of a genuine, region-wide development strategy.
ABOUT THE AUTHOR
Marcos Troyjo
Reading Time: 5 minutesTroyjo is the Robert E. Wilhelm Fellow at MIT’s Center for International Studies. He is a former president of the New Development Bank and Brazil’s former special secretary for foreign trade and international affairs.
The Donroe Doctrine’s China Paradox
Washington’s increasing focus on political alignment may be giving the region more reasons to keep China close.
China’s Green-Tech Push in Latin America Is Gaining Traction
A surge of investment in the region is set to intensify, even as the hemisphere turns rightward.