

For more than a year, the United States has reshaped global and hemispheric trade with a tariff policy that has made market access, supply chains, and regulatory alignment top priorities for governments worldwide. The new scenario has also incentivized some Latin American companies to accelerate or pursue expansion into the world’s largest economy, building on a decades-long trend.
The U.S. remains, by a wide margin, Latin America’s most consequential economic partner and its deepest source of capital-market access, and its recent tariff policy has had uneven effects across the region’s economies. Mexico has lived with near-constant anxiety about the future of the USMCA, now on an annual review basis. Brazil has borne significant costs, while Argentina, Uruguay, Ecuador, and several Central American economies have gained opportunities to increase exports and attract investment by aligning more closely with U.S. standards.
Against this complex backdrop, multilatinas—Latin America-based companies seeking to expand beyond their borders—have chosen integration. Rather than lobby, retaliate, or retreat, they are doing what smart foreign companies have always done when the U.S. matters this much: becoming, in a legal and operational sense, more American.
The strategic response to the new environment is visible from Monterrey to Buenos Aires. It has taken three broad forms—industrial deepening, financial integration, and structural realignment. None of this is defensive. It is a bet that it is worth building in the hemisphere’s deepest, most stable, and most creditworthy market—with American workers, American regulators, and American customers.
A recent study by the Inter-American Development Bank highlighted that multilatinas now operate in 116 countries and across a wide range of sectors, from food, energy, and banking to aerospace. The question is whether these companies can turn these U.S. and global inroads into a durable competitive advantage.
Betting on the U.S.
The most consequential moves are coming from groups treating the U.S. as a home market rather than an export destination. Mexico’s Grupo Bimbo, the world’s largest baking company, announced in May plans to invest approximately $1 billion in the U.S. from 2026-2028. Its subsidiary Bimbo Bakeries USA already operates more than 50 manufacturing plants and employs over 20,000 people in the U.S.
The Italian-Argentine conglomerate Techint Group has moved in a similar direction. In January, Techint’s Tenaris unit reactivated heat-treatment and finishing lines at its Pennsylvania mill to supply steel pipes for the U.S. energy sector. Another unit, Ternium, continues to build out steelmaking capacity in Pesquería, Mexico, closely tied to U.S. auto and construction demand. Brazil’s Gerdau, another global steel producer, is following a similar logic: Its $51.5 million expansion in Texas is positioned to serve U.S. data-center and renewable-energy build-out.
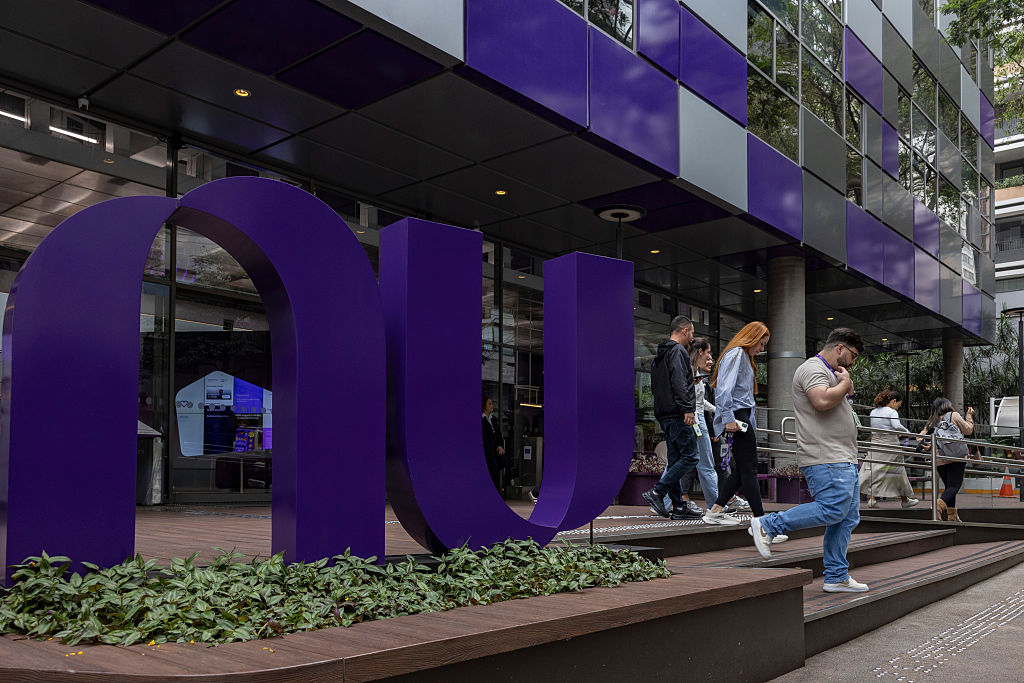
Nu Holdings, Latin America’s largest digital bank, with Brazilian roots and operations in Mexico and Colombia, is helping drive financial integration. Earlier this month, it opened for business in the U.S. through a partnership with Lead Bank. Nu Holdings’ own U.S. national bank charter was conditionally approved by the Office of the Comptroller of the Currency in January.
Among the firms strategically reshaping their corporate maps, Colombia’s Cementos Argos is the clearest example. In April, the company announced plans to separate its operations into Argos Latam—serving Colombia, Central America and the Caribbean—and Argos Materials, based in and serving the U.S.
Others are likely to follow this template as their U.S. businesses reach the scale at which independent capital structures and independent regulators become an advantage. Mexican restaurant operator Alsea, which runs Starbucks across Latin America and Europe under licensing agreements recently extended to 2046, points to a related model: not a split, but a long-term commercial partnership with a U.S. brand as the growth engine.
Years in the making
The first multilatina enterprise emerged a century ago in Argentina, then the region’s most prosperous economy. Bunge y Born (which at the time controlled a fifth of the world’s wheat trade) extended into Brazil to cut freight costs. Argentina lost that early promise to political polarization and mismanagement, and its firms turned inward.
The outward gaze returned in the 1990s as Chilean companies pushed into Argentina, Peru, Colombia and Brazil in retail, banking and energy. Falabella retail stores in places like Buenos Aires and Lima became nodes in a deliberate Latin network.
Colombia’s Grupo Empresarial Antioqueño conglomerate followed a similar pattern, internationalizing through a Central American acquisition in 2006. Colombia’s Cementos Argos, anchored in Cemento Panamá, pursued multinational expansion across Latin America and the Caribbean and developed its U.S. export business into a full-fledged American cement and concrete operation.
Chile-based Cencosud took this evolution a step further with its 2022 acquisition of a 67% stake in The Fresh Market, a premium U.S. grocery chain, for $676 million. It was more than a financial investment: Cencosud acquired a controlling stake in an established American operator, retained local management, and initially partnered with financial investors. The transaction showed how the mature Chilean multilatina had evolved, from exporting a retail format across neighboring markets to acquiring a platform in the world’s largest and most demanding consumer market.
The multilatinas’ investment wave is reflected in the growing amount of foreign direct investment (FDI) into the U.S. over the last half-decade.
Pragmatism pays off
The region’s homegrown transnational corporations were forged in the crucible of domestic turbulence and are now looking outward not only for profit, but for stability.
The discipline that instability produced is precisely what allows multilatinas to thrive alongside—and increasingly inside—the U.S. The relationship is not adversarial, but productive. The firms that understand this are building bakeries in Dallas and steel mills in Texas and Pennsylvania and have boards that meet in both Monterrey and Dallas.
A profound irony is that the very volatility that once derailed Argentina’s early promise has, a century later, given its neighbors a formidable competitive edge. These companies have proven that institutional fragility need not be a death sentence; it can be a rigorous training ground for a higher order of efficiency. As the global order grows increasingly unpredictable, multilatinas’ pragmatism may prove their greatest strength: an ability to remain focused on their business even as the ground beneath them remains unstable.
ABOUT THE AUTHOR
Conrado Tenaglia
Reading Time: 4 minutesTenaglia is a lawyer and former partner at Linklaters LLP. He was a 2025 visiting scholar at Harvard Law School.
What Mexico Can (and Cannot) Control
Mexico can focus on navigating tensions with the United States while putting its own house in better order, writes a former policymaker.